How to Teach Your Kids About Money Without Lecturing
“Money doesn’t grow on trees.” “Do you think I’m made of money?” “We can’t afford that.” Most of us absorbed our financial education through parental sighs and checkout-line negotiations — a curriculum of anxiety, not understanding. If you want your kids to have a healthier relationship with money than lectures ever produced, the secret is counterintuitive: stop talking about money and start letting them use it.
This guide gives you an age-by-age playbook for teaching kids about money through experience rather than lectures: the core concepts each age can grasp, practical systems that run themselves, the mistakes that backfire, and how to handle the hard questions.
Why Lecturing Fails (the Learning Science)
Children learn financial behavior the way they learn everything: through experience, modeling, and consequences — not through explanations. Research on financial socialization consistently shows that kids’ money habits correlate far more with what parents do than what they say. The parent who lectures about saving while impulse-buying daily teaches the impulse-buying; the lecture is just background noise.
This is actually liberating: you don’t need the perfect speech. You need systems where kids make small money decisions, experience the outcomes, and build judgment through practice — with stakes low enough that mistakes are lessons, not disasters. A $5 mistake at age 8 prevents a $5,000 mistake at 28.
Ages 3–6: Money Is Real and Finite
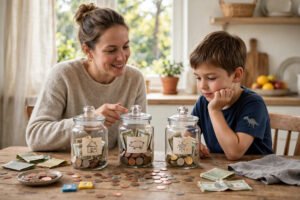
The only concepts that matter here: money is exchanged for things, and when it’s gone, it’s gone. Use a clear jar (not a piggy bank — kids need to see the money) for saving toward a visible goal. Let them hand cash to cashiers. When they ask for something at the store, the answer isn’t a lecture on economics — it’s “that’s not what we’re buying today,” said calmly and consistently.
Play is the curriculum: play store, restaurant, lemonade stands. The goal isn’t financial literacy — it’s normalizing money as a neutral tool rather than a source of parental stress. Kids who hear constant money anxiety absorb the anxiety, not the lesson.
Ages 7–12: Earning, Choosing, and Consequences
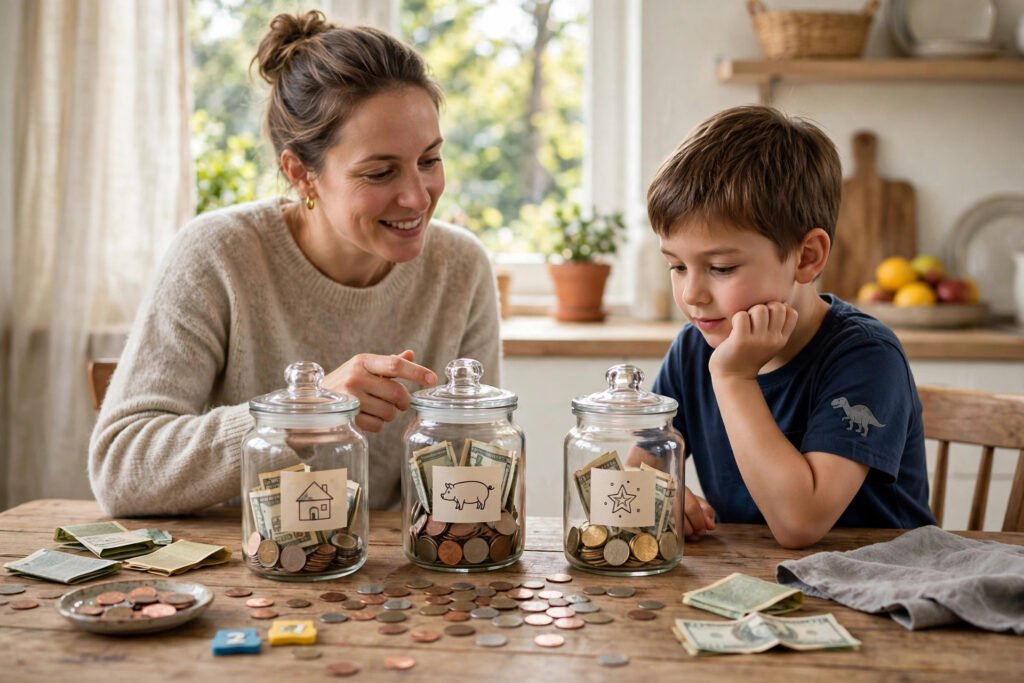
This is the golden window — kids are concrete thinkers who thrive on systems. An allowance tied to age, not chores (chores are family citizenship; paid extra jobs are above-and-beyond): a common formula is $1 per week per year of age, split three ways — spend, save, share. The three jars make values tangible without a single lecture.
Let them blow it. This is the hardest and most important part. When your 9-year-old spends all their money on a toy that breaks in a day, resist the rescue. The disappointment teaches more than any warning could — and it costs $12 instead of $12,000 later. Parents who always intervene raise kids who never develop judgment; they just develop dependence on parental judgment.
Introduce earning: extra jobs for pay, neighborhood work, small entrepreneurial ventures. Earning transforms money from “what parents give” to “what effort produces” — the single most important financial concept, learned through sore muscles rather than speeches. Involve them in real household economics too — grocery budgeting with a list and a limit turns a chore into a masterclass.
Ages 13–17: Real Money, Real Systems
Teenagers can handle — and need — genuine financial responsibility. A bank account with a debit card (many banks offer teen accounts with parental oversight) moves money from abstract to real. A clothing budget: give them the seasonal clothing money as a lump sum and let them manage it — the teen who blows it on one pair of sneakers learns budgeting faster than any app could teach.
First job earnings: establish the habit early — a percentage to savings automatically, the rest theirs. Teens who start this at 16 enter adulthood with the savings reflex installed; those who don’t spend a decade building it. Introduce investing basics: a custodial account with a small amount in a broad index fund, watched together quarterly. Compound growth demonstrated with their own money beats every explanation of compound growth ever given.
The college money talk: be concrete about what you’ll contribute and what they must cover — vague reassurances produce seniors making uninformed borrowing decisions. Saving for big goals is a skill teens can practice now, with cars, trips, or college expenses as the curriculum.
The Conversations (When They Ask)
Kids ask hard money questions — answer honestly at their level. “Are we rich/poor?”: “We have enough for what we need and some of what we want, and we’re careful with it” — honest without burdening them with adult anxieties. “Why can’t we have what they have?”: “Different families make different choices with their money” — no judgment of others, no shame about yours. “How much do you make?”: answer in ranges or with context when they’re old enough (“enough to cover our needs and save for the future”) — secrecy teaches that money is shameful; age-appropriate openness teaches it’s manageable.
Model the behavior visibly: let them see you budgeting, comparing prices, saying no to yourself, and giving to causes. The manners you model and the money habits you model are absorbed through the same channel — observation, not instruction.
Mistakes That Backfire
Using money as punishment/reward for behavior: docking allowance for bad grades tangles money with control and teaches nothing about either. Rescuing every mistake: as covered — intervention prevents learning. Fighting about money in front of kids: they absorb the conflict, not the content; disagree privately. Waiting until they’re “old enough”: by the time you think they’re ready, they’ve already formed habits from observation — start early, start small. Expecting perfection: your kid will make dumb money choices. That’s the tuition. Celebrate the learning, not the mistake-free record.
The Consumer Financial Protection Bureau’s family finance resources and the federal government’s MyMoney.gov financial literacy site both offer age-by-age activities that complement the systems above.
Conclusion
Teaching kids about money without lecturing means building systems where money is real, finite, earned, and consequential — clear jars for little ones, three-way splits and earned income for middle years, real accounts and budgets for teens — while modeling the behavior you want and letting small mistakes teach big lessons. You don’t need the perfect words. You need to hand them the money, step back, and let experience do the teaching. The lectures they’ll forget by dinner; the $12 mistake will shape them for decades.
Frequently Asked Questions
Should kids get an allowance for chores?
Most experts recommend separating them: basic chores are family contributions (unpaid), while an allowance teaches money management and extra jobs can earn extra pay. Tying all money to chores teaches kids to negotiate every contribution — “how much to clear my plate?”
What age should kids get a bank account?
Many banks offer custodial or teen accounts from around age 13 (some younger with parental control). The right age is when they’re handling enough money to need organization — often coinciding with first jobs or larger gifts.
How do I teach teens about credit cards?
Start with a debit card and the rule “never spend what you don’t have,” then explain credit as borrowing from your future self — with interest as the price. An authorized-user card with a low limit, monitored together, can build credit history safely before 18.
Should I tell my kids our income?
Age-appropriate honesty beats secrecy: young kids need “we have enough and we’re careful,” teens can handle ranges and context. The goal is demystifying money, not burdening them with adult financial stress.
What’s the biggest money mistake parents make with kids?
Rescuing them from every financial mistake. The $10 toy that breaks, the blown clothing budget, the impulse purchase regretted — these are the cheapest financial educations available. Intervention feels like love; it’s actually theft of the lesson.