Condo vs. House for Beginners: Which Should You Buy?
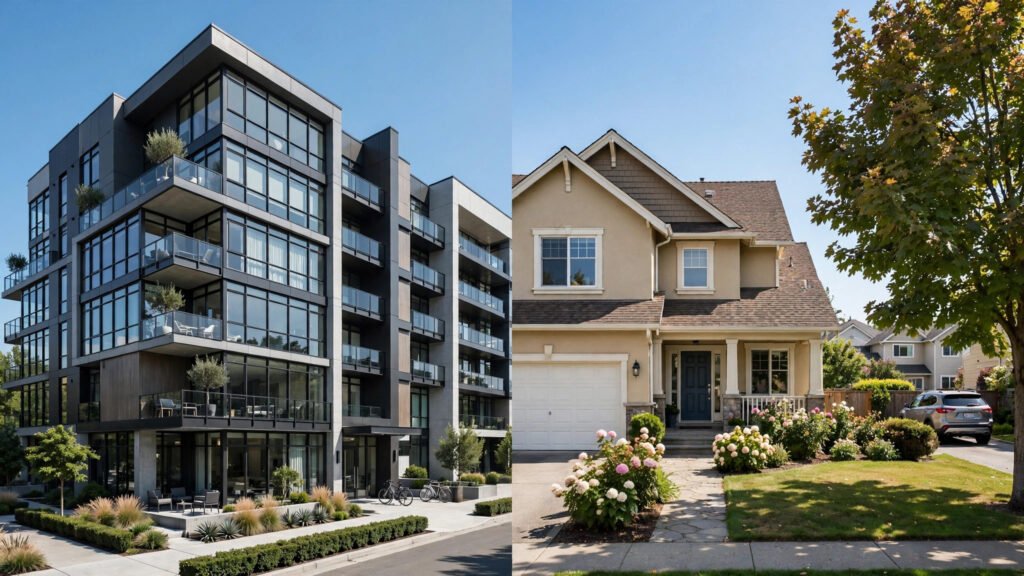
For first-time buyers staring at intimidating house prices, the condo pitches itself beautifully: homeownership at a discount, no yard work, amenities you’d never afford in a house. The single-family home counters with the American dream itself: your land, your rules, room to grow. In 2026, with affordability stretched thin across much of the country, this isn’t an abstract debate — it’s the decision thousands of beginners face every weekend at open houses.
This guide compares condos and houses honestly across the dimensions that actually determine satisfaction: true cost, lifestyle fit, investment performance, and the lifestyle traps each one hides.
The Price Illusion: Why Condos Look Cheaper Than They Are
The sticker price is where condos win — often 15–30% less than comparable houses in the same area. But the sticker isn’t the cost. HOA dues, the condo’s defining expense, run hundreds of dollars monthly and rise over time; special assessments for roof replacements or facade work can land five-figure bills with 30 days’ notice. A $280,000 condo with $450/month HOA dues costs roughly the same monthly as a $330,000 house — a comparison buyers must run before falling for the list price.
Houses have their own hidden costs, of course: maintenance averages 1–2% of home value annually, yards need care or paid help, and every system (roof, HVAC, plumbing) is your problem alone. The honest math: condos trade unpredictable big expenses for predictable monthly ones; houses trade monthly predictability for control. Understanding what actually builds home value helps whichever path you choose.
Lifestyle: The Real Deciding Factor
Strip away the finances and the choice is about how you want to live:
Choose the condo if: you travel frequently and want lock-and-leave simplicity; you dread maintenance and yard work; you value amenities (gym, pool, security) you’d never buy solo; you’re buying in a dense urban area where houses are impractical; or you’re a first-timer who wants homeownership training wheels. Condo living is genuinely liberating for the right personality — many owners describe the maintenance-free lifestyle as the best money they spend.
Choose the house if: you need space (kids, dogs, hobbies, home office); you want control over your property (renovations, pets, noise, parking); you value privacy and outdoor space; or you’re in a market where land itself appreciates strongly. A house gives you creative control no HOA board can veto — for better and occasionally worse.
The tiebreaker question: where will you be in five years? If kids, remote work needs, or space requirements are likely to change, buy for the life you’re growing into, not just the one you have. Transaction costs punish short stays brutally, so a five-year minimum horizon should be part of the decision, not an afterthought.
The Investment Case: Appreciation, Fees, and Resale
Historically, single-family homes appreciate faster than condos in most American markets — land is the appreciating component, and condos include very little of it. During downturns, condos also tend to fall further and recover slower, partly because investors dump them first and partly because HOA distress (delinquencies, deferred maintenance) compounds price declines.
Condos carry specific resale risks beginners miss: HOA health — underfunded reserves or pending litigation can make units unmortgageable (lenders check); owner-occupancy ratios — buildings heavy with renters face financing restrictions; special assessments — looming big-ticket repairs get priced into what buyers will pay; and oversupply — new condo towers nearby can undercut your resale for years.
None of this makes condos bad investments — well-located units in healthy buildings in supply-constrained cities perform fine. But houses are the simpler, more forgiving investment, which matters enormously for beginners who can’t underwrite HOA financials like professionals. The Consumer Financial Protection Bureau’s home-buying resources walk through evaluating ownership costs that many first-timers overlook.
The HOA: Condos’ Defining Relationship
Buying a condo means marrying an HOA, so date before committing. Request and actually read: the HOA budget and reserve study (are they saving for the roof or praying?), meeting minutes from the last year (drama leaves paper trails), the rules and CC&Rs (pet limits, rental caps, renovation restrictions — the fine print that governs your daily life), and any pending special assessments or litigation.
Red flags: reserves under 30% funded, a pattern of deferred maintenance visible in common areas, special assessments every couple of years (a sign of chronic underfunding), active lawsuits, or boards that won’t share documents. A healthy HOA is invisible; a sick one is the most expensive relationship in your financial life. This due diligence is non-optional — even cosmetic choices may need HOA approval, so know the rules before you buy the paint.
The 2026 Market Context
Current conditions add nuance. In many markets, condo inventory has grown faster than single-family inventory, giving condo buyers negotiating power rare in recent years — price cuts and seller concessions that house buyers can only dream of. Insurance costs, particularly in coastal and disaster-prone states, are reshaping the math for both: houses carry individual policies with soaring premiums, while condos split master-policy costs (but face their own assessment risks when master policies spike).
Interest rates affect both equally on the mortgage side, but the lower condo price point means rate movements change monthly payments less in absolute dollars — a small comfort that’s genuinely meaningful for stretched first-time budgets.
HUD’s homebuyer resources explain FHA condo approval requirements and the consumer protections that apply to buyers.
Conclusion
For most beginners in 2026, the honest answer is: a house is the better investment and the more flexible life asset, while a condo is the better lifestyle fit for maintenance-averse, amenity-loving, or budget-constrained buyers in the right building. The wrong choice isn’t a category — it’s buying either without running the true-cost math, reading the HOA documents, or thinking five years ahead. Buy the home that fits the life you’re building, verify the finances like an auditor, talk to current owners in any building you’re considering, and you’ll be fine in either structure. The building matters less than the homework.
Frequently Asked Questions
Are HOA fees worth it?
Sometimes — divide the fee by what you’d pay separately for the covered services (exterior insurance, water, amenities, maintenance). Well-run HOAs with healthy reserves deliver genuine value; poorly run ones are money pits. The fee itself tells you nothing; the budget and reserves tell you everything.
Do condos appreciate as fast as houses?
Generally no — single-family homes have historically appreciated faster in most U.S. markets because land (which condos barely include) drives appreciation. Well-located condos in supply-constrained cities can perform well, but houses are the safer appreciation bet.
Can I Airbnb my condo?
Maybe — many HOAs restrict or ban short-term rentals, and cities increasingly regulate them. Check the CC&Rs and local laws before assuming rental income. Never buy a condo counting on Airbnb income you haven’t verified is allowed.
What’s a healthy HOA reserve fund?
Look for reserves at least 70%+ funded per the reserve study, with regular contributions — not special assessments — funding future repairs. Under 30% funded is a red flag signaling coming assessments or deferred maintenance.
Is a condo or house better for a first-time buyer?
It depends on the buyer, not the category. Budget-constrained urban buyers who value low maintenance often thrive in condos; buyers needing space, control, or maximum appreciation usually do better with houses. Run the true-cost math for your specific options before deciding.