Roth vs. Traditional IRA: What’s the Real Difference?
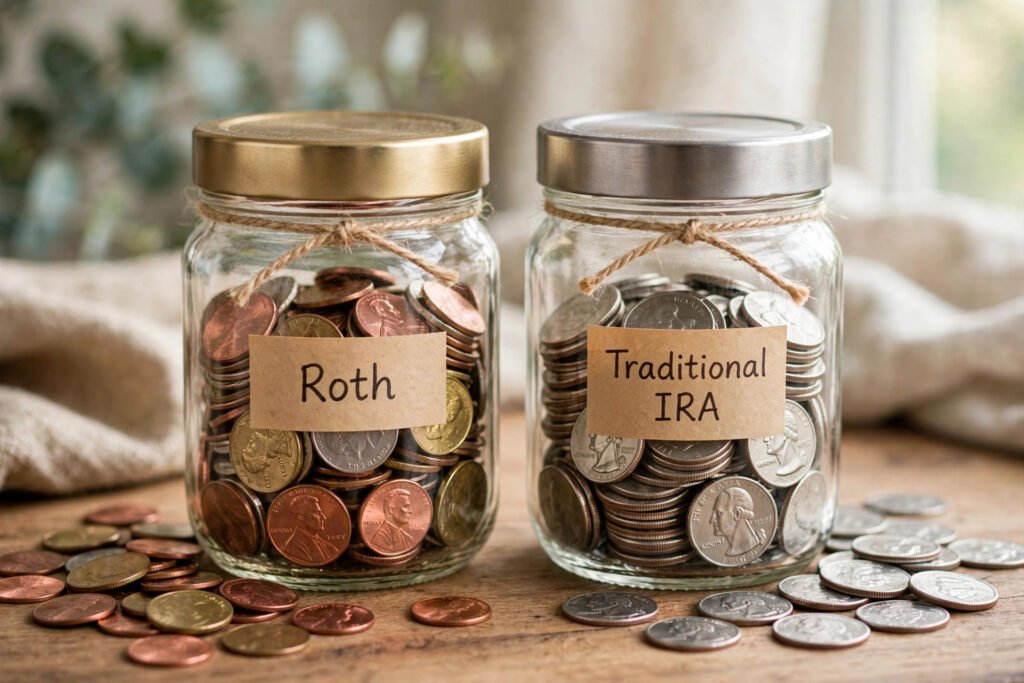
Roth or traditional? It’s the most common IRA question in America, and the most misunderstood. The choice affects how much tax you pay over your lifetime — potentially tens of thousands of dollars — yet most people pick based on vibes (“Roth sounds better”) or whatever their coworker chose. The real answer comes down to one variable: your tax rate now versus your tax rate in retirement. Here’s how to think it through properly.
The core difference (it’s about when you pay tax)
- Traditional IRA: contributions may be tax-deductible now; you pay tax on withdrawals in retirement. Pay later.
- Roth IRA: contributions are after-tax (no deduction now); qualified withdrawals in retirement are completely tax-free — including all the growth. Pay now.
Same contribution limits ($7,000 for 2026, $8,000 if 50+), same investment options, same early-withdrawal penalties on earnings (generally 10% before 59½ plus taxes, with exceptions). The only fundamental difference is the timing of taxation — but that timing changes everything.
The decision rule: compare tax rates
If your tax rate is higher now than it will be in retirement → traditional usually wins (deduct at the high rate, withdraw at the low rate).
If your tax rate is lower now than it will be in retirement → Roth usually wins (pay tax at today’s low rate, enjoy tax-free withdrawals later).
Practical translations:
- Young, early-career, lower income → Roth. You’re likely in the lowest bracket of your life. Pay 12% now to avoid 22–24%+ later.
- Peak earning years, high bracket → traditional (if deductible — see income limits below). Deduct at 32–37%, withdraw at lower retirement rates.
- Expecting a pension or large 401(k)? Your retirement “income” may be higher than you think — tilting toward Roth.
- Expecting lower retirement spending? Traditional’s deduction likely wins.
The factors beyond tax rates
Roth advantages people underestimate
- No required minimum distributions (RMDs): traditional IRAs force withdrawals starting at 73–75, whether you need the money or not — potentially pushing you into higher brackets and increasing Medicare premiums. Roth IRAs have no RMDs for the original owner, ever.
- Tax diversification: having both pre-tax and Roth money gives you control in retirement — pull from traditional up to a bracket limit, then Roth for the rest. Flexibility is valuable.
- Estate planning: Roth IRAs are superior inheritances — heirs get tax-free money (though they must empty it within 10 years under current law).
- Effective higher contributions: $7,000 in a Roth is worth more than $7,000 in a traditional, because the Roth’s $7,000 is after-tax — you’re sheltering more real wealth.
- Contribution flexibility: Roth contributions (not earnings) can be withdrawn anytime without tax or penalty — a backdoor emergency feature traditional IRAs lack.
Traditional advantages people underestimate
- The deduction’s immediate value: a $7,000 deduction at 24% = $1,680 back in your pocket this year — money you can invest, spend, or use to fund the emergency fund.
- Most people do face lower rates in retirement: no more payroll taxes, often lower spending, and control over withdrawal timing.
- State tax arbitrage: deduct while working in high-tax California or New York, withdraw in retirement in no-tax Florida or Texas. This alone can be worth 5–10%.
Income limits and eligibility (2026 essentials)
- Roth IRA: direct contributions phase out at higher incomes (single filers ~$150k–$165k; married ~$236k–$246k — verify current-year figures). Above the limit? The backdoor Roth (contribute non-deductible to traditional, immediately convert) remains legal and widely used.
- Traditional IRA deduction: if you (or your spouse) are covered by a workplace plan, deductibility phases out at moderate incomes. Without workplace coverage, it’s fully deductible regardless of income.
- Neither has an age limit for contributions anymore — you can contribute at any age with earned income.
Freelancers and the self-employed should read our guide to retirement without an employer plan — the Solo 401(k) vs. IRA interplay matters here. And the IRS’s IRA resources have the authoritative current-year limits.
The “both” strategy (what most people should actually do)
Here’s the secret the Roth-vs-traditional debate obscures: you don’t have to choose just one. The $7,000 limit is combined across both types — you can split it ($3,500 Roth + $3,500 traditional, or any mix). Most people’s optimal strategy:
- Early career / low bracket: 100% Roth.
- Mid-career / higher bracket: traditional 401(k) for the deduction + Roth IRA on the side = automatic tax diversification.
- Peak years: mostly traditional (deductions at top rates).
- Low-income years (sabbatical, early retirement, grad school): Roth conversions — move traditional money to Roth while your bracket is temporarily low.
This lifecycle approach beats picking one type forever. Coordinate with your broader tax picture — our tax management guide and deduction strategies help, and overall financial planning ties it together.
Common mistakes
- Choosing Roth because “tax-free sounds better” without comparing rates — in a high bracket, the traditional deduction often wins mathematically. Run your actual numbers; don’t go by vibes.
- Ignoring the backdoor Roth when income exceeds direct Roth limits.
- Forgetting RMDs: large traditional balances create forced taxable income at 73+ — Roth conversions in your 60s can defuse this.
- Raiding the Roth early: yes, contributions are withdrawable — but every dollar removed is decades of tax-free compounding destroyed.
- Analysis paralysis: either IRA beats no IRA. If genuinely torn, split 50/50 and move on — the contribution matters more than the type. And revisit annually: a job change, marriage, or move to a different tax state can flip the optimal choice, so make the Roth-vs-traditional question part of your yearly financial review rather than a once-in-a-lifetime decision.
The SEC’s Investor.gov retirement resources are excellent free companions for these decisions.
The bottom line
Roth vs. traditional comes down to tax rates: pay now (Roth) when your rate is low, deduct now (traditional) when your rate is high. Young and lower-earning → Roth. Peak earning years → traditional (if deductible). But the real pro move is lifecycle-based: Roth early, mixed in the middle, strategic conversions in low-income years — building tax diversification that gives you control in retirement. And remember: the best IRA is a funded one. Decide this week, automate the contributions, and let decades of compounding do the heavy lifting for your future self, starting today.
Frequently Asked Questions
What’s the difference between a Roth and traditional IRA?
Traditional: tax-deductible contributions now, taxed withdrawals later. Roth: after-tax contributions now, tax-free qualified withdrawals in retirement. Same limits and investment options.
Is Roth or traditional better for young investors?
Usually Roth — young investors are typically in lower tax brackets, so paying tax now at 12% beats deducting later, plus decades of tax-free growth and no RMDs.
What if I earn too much for a Roth IRA?
Use the backdoor Roth: contribute non-deductible dollars to a traditional IRA, then convert to Roth. It’s legal, common, and takes minutes with most brokerages.
Can I have both a Roth and traditional IRA?
Yes — the $7,000 annual limit ($8,000 if 50+) is combined across both. Splitting contributions gives you tax diversification, which most planners recommend.
Do Roth IRAs have required minimum distributions?
No — Roth IRAs have no RMDs for the original owner, a major advantage over traditional IRAs (which force withdrawals starting at age 73–75). This makes Roths superior for estate planning and tax control.