What Are Sinking Funds and How Do You Set Them Up?
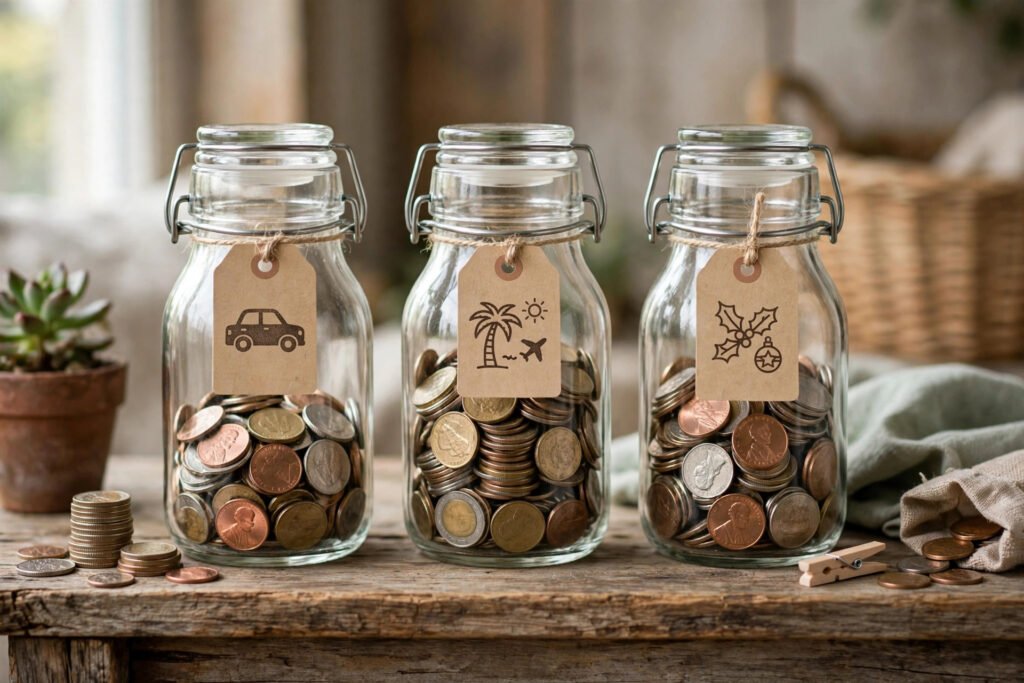
Christmas arrives every December. Your car needs new tires eventually. The annual insurance premium is due in March. None of these are surprises — yet every year, they feel like emergencies, blowing up budgets and landing on credit cards. Sinking funds are the elegantly simple system that fixes this: savings buckets for predictable future expenses, funded a little each month, so “surprise” bills become routine transfers. It’s one of the highest-impact budgeting techniques nobody talks about.
What sinking funds are
A sinking fund is money you set aside regularly for a known future expense — as opposed to an emergency fund, which covers unknown surprises. The name comes from corporate finance (companies “sink” money into funds to retire bonds), but the personal version is beautifully simple: divide a future cost by the months until it’s due, save that amount monthly, and the money is there when the bill arrives.
Example: your $1,200 annual car insurance premium ÷ 12 = $100/month into the “car insurance” sinking fund. When the bill arrives, you transfer — no stress, no credit card, no “emergency.”
Sinking fund vs. emergency fund vs. savings
- Emergency fund: unknown surprises (job loss, medical emergency). Don’t touch for predictable bills.
- Sinking funds: predictable future expenses (insurance premiums, holidays, car maintenance). Planned and scheduled.
- General savings: goals and wealth-building (down payment, retirement).
All three are necessary; they serve different jobs. Raiding the emergency fund for Christmas is the classic category error sinking funds prevent.
What to create sinking funds for
Walk through your last 12 months of “unexpected” expenses — most were predictable. Common sinking funds:
- Annual/semi-annual bills: car insurance, home insurance, property taxes, subscriptions (Amazon Prime, etc.)
- Car costs: maintenance, tires, registration — budget ~$100–$150/month for the average car
- Home maintenance: the 1% rule (1% of home value yearly) divided by 12
- Holidays and gifts: Christmas, birthdays, anniversaries — total last year’s spending, divide by 12
- Travel: your annual vacation budget, funded monthly
- Medical: deductibles, dental work, glasses — predictable-ish costs smoothed monthly
- Kids: school supplies, activities, summer camps
- Pets: annual vet visits, grooming
- Tech replacement: phones, laptops on a 3–4 year cycle
How to set them up: the practical system
Step 1: List and cost them
Brain-dump every predictable irregular expense. For each: annual cost (use last year’s actuals — check bank statements, not memory; memory underestimates by ~30%) and due date.
Step 2: Calculate monthly amounts
Annual cost ÷ months until due. A $600 holiday budget starting in January = $50/month. A $900 insurance bill due in 6 months = $150/month. The math is trivial; doing it is the breakthrough.
Step 3: Choose your structure
- Separate savings accounts: many online banks (Ally, Marcus, etc.) let you create multiple named “buckets” within one account — ideal. One login, many labeled funds.
- One account + spreadsheet: simpler banking, but requires tracking discipline. Works if you’re spreadsheet-inclined.
- Cash envelopes: the classic Dave Ramsey method — physical envelopes per category. Powerful psychologically, impractical for large amounts.
Recommended: one high-yield savings account with named sub-buckets. It earns 4–5% while you wait, stays FDIC-insured, and the labels prevent “borrowing” between funds — which our personal finance system treats as a cardinal sin.
Step 4: Automate transfers on payday
Total your monthly sinking fund amounts and automate one transfer on payday, then split into buckets (many banks auto-split). Automation is non-negotiable — manual “I’ll transfer later” fails within two months.
Step 5: Spend from the funds guilt-free
This is the psychological payoff: when Christmas comes, you spend the Christmas fund without guilt or budget damage — because you already “paid” for it monthly. Sinking funds convert anxiety into routine.
How sinking funds change your budget
Before sinking funds, your budget has a hidden lie: months look affordable because big irregular bills aren’t in them. A $4,000/month budget that ignores $6,000/year of irregular bills is really a $4,500/month budget lying to itself — and the $500/month lie surfaces as credit card debt every December and April.
Sinking funds fix this by making the true monthly cost visible: add up all funds’ monthly amounts and that’s your real baseline. It’s sobering the first month — and liberating every month after. Pair this with honest grocery budgeting and goal-based saving for a complete system.
A year with sinking funds: the before and after
Consider the Martinez family before sinking funds: January’s car insurance bill ($1,100) went on a credit card; July’s AC repair ($850) drained savings; December’s Christmas ($1,400) went on a store card at 24% APR. Total “surprise” damage: $3,350 in debt plus interest, plus months of stress. After adopting sinking funds — $92/month for insurance, $100/month for home maintenance, $117/month for holidays — the same bills arrived and were paid from labeled buckets. Same income, same expenses, radically different outcome: zero new debt, zero stress, and the credit cards stayed at zero. The money didn’t change; the timing of setting it aside did. That’s the entire magic of sinking funds — transforming lumpy annual costs into smooth monthly habits.
Common mistakes
- Underestimating costs: use last year’s actuals from bank statements, then add 10% buffer. Optimism is the enemy.
- Too many micro-funds: 5–10 funds is manageable; 25 is administrative theater. Group small items (“household annuals”).
- Raiding funds for other purposes: the Christmas fund is not a sale fund. Respect the labels.
- Forgetting to adjust: review annually — insurance rises, kids’ activities change, cars age (maintenance funds should grow as cars get older).
- Skipping months: a skipped month isn’t saved money — it’s debt to your future self, with the bill arriving on schedule regardless.
The CFPB’s budgeting tools complement this system well for the overall budget picture.
The bottom line
Sinking funds are simple: list your predictable irregular expenses, divide each by the months until due, automate monthly transfers into labeled buckets, and spend guilt-free when bills arrive. They eliminate the entire category of “unexpected” expenses that aren’t actually unexpected — ending the cycle of credit-card Christmases and “emergency” car repairs. It’s the least glamorous and most transformative budgeting upgrade most households can make. Start this weekend: list your irregular bills, do the division, and automate the first transfer.
For official guidance, see Ask CFPB’s budgeting guides.
Frequently Asked Questions
What are sinking funds?
Regular savings set aside for known future expenses — car insurance, holidays, home maintenance. You divide the expected cost by months until due and save that amount monthly, so the money’s ready when the bill arrives.
How are sinking funds different from an emergency fund?
Emergency funds cover unknown surprises (job loss, medical emergencies). Sinking funds cover predictable expenses (annual premiums, Christmas, car maintenance). You need both — they serve different purposes.
How many sinking funds should I have?
5–10 is the sweet spot for most households: annual bills, car maintenance, home maintenance, holidays/gifts, travel, medical, and a few personal categories. Group small items to avoid administrative overload.
Where should I keep sinking fund money?
A high-yield savings account with named sub-buckets — FDIC-insured, earning 4–5%, with labels that prevent raiding one fund for another purpose.
What if I can’t afford to fund all my sinking funds?
Start with the most urgent (nearest due dates), fund proportionally if needed, and treat the shortfall as information: your true monthly expenses exceed your income, and the budget — not the funds — needs fixing.