Selling and Buying a Home at the Same Time: A Survival Guide
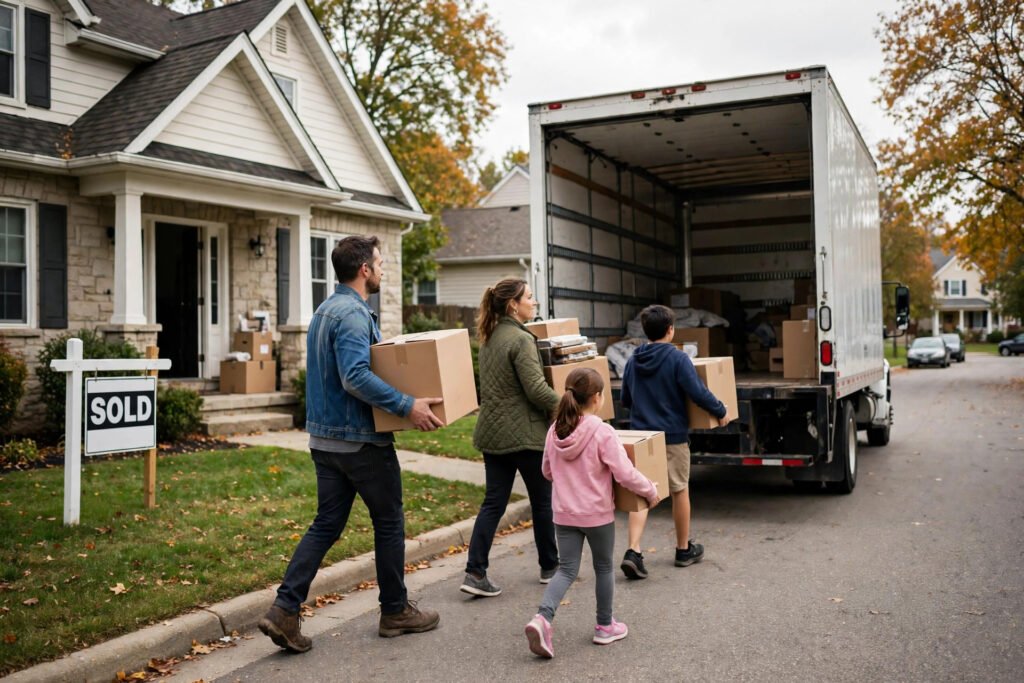
Selling your current home while buying the next one is the real estate equivalent of changing planes mid-flight: thousands of Americans do it every year, and it works — but only with careful choreography. Get the timing wrong and you’re either homeless between closings, paying two mortgages, or making a desperate offer with no leverage. The good news is that this is a solved problem. Buyers, sellers, agents, and lenders have developed a playbook of strategies — contingencies, bridge loans, rent-backs, and precise sequencing — that turn chaos into a manageable process. Here’s how to sell and buy at the same time without losing your mind or your money.
Strategy 1: Sell First, Then Buy (Safest, Most Inconvenient)
The simplest sequence is selling your current home before buying the next. You know exactly how much equity you’re working with, your offer on the new place carries no sale contingency (making it stronger in competitive markets), and you avoid ever carrying two mortgages. For buyers who need every dollar of equity for the down payment, this is often the only realistic path.
The obvious downside: you need somewhere to live between closings. Options include a short-term rental, an extended-stay hotel, or generous relatives — plus storage for your belongings and potentially two moves. That interim period typically lasts one to three months and costs a few thousand dollars, which stings but is predictable. To minimize the gap, negotiate a rent-back agreement (more on that below) letting you stay in your sold home as a tenant for 30–60 days after closing while you finalize the purchase. If your equity picture is the constraint, start by mapping exactly what you’ll net — our guide to saving for a big purchase covers the budgeting discipline that makes the down payment math work.
Strategy 2: Buy First, Then Sell (Most Convenient, Most Expensive)
Buying before selling means one move, no temporary housing, and the luxury of house-hunting without desperation. In hot markets, it also lets you pounce on the right home instead of watching it sell while your own listing languishes. This strategy works best for buyers with enough cash or income to qualify for two mortgages simultaneously — lenders will count both payments in your debt-to-income ratio unless your current home is under contract.
The risks are real: carrying two mortgages burns cash fast, and if your old home sits unsold, the pressure to accept a lowball offer grows monthly. Mitigate this by pricing your current home to sell rather than to test the market — an aggressive, market-smart price informed by real comparable sales. Some buyers use a bridge loan, a short-term loan secured against their current home’s equity, to fund the new down payment; these are convenient but pricey, with higher rates and fees than conventional financing. Another increasingly common tool is the “buy before you sell” programs offered by companies and some brokerages, which effectively front you the equity — convenient, but read the fee structure carefully, because convenience here costs real money.
Strategy 3: The Contingent Offer (Elegant When It Works)
A home-sale contingency makes your purchase offer conditional on selling your current home. When accepted, it’s the cleanest solution: one coordinated timeline, no double housing costs. In buyer’s markets or balanced markets, sellers accept these routinely. Your agent can strengthen a contingent offer by showing your current home is already listed, priced well, or even under contract — a “contingent on closing” offer is far more attractive than “contingent on selling.”
The catch: in competitive seller’s markets, contingent offers often lose to cleaner ones. Sellers fear the domino risk — if your buyer flakes, their sale collapses too. Many sellers counter with a “kick-out clause” (also called a bump clause), letting them keep marketing the home and giving you 48–72 hours to remove your contingency if another offer arrives. If you go this route, get your current home listed and showing-ready before you start offering, and price it to move. An experienced local agent is worth their weight here — how real estate agents use AI to sell homes shows how top agents now price and market with data tools that genuinely speed up sales.
The Sequencing Playbook: Making the Timelines Meet
Whichever strategy you choose, the mechanics of coordination matter enormously. Start by getting pre-approved for the purchase with full disclosure to your lender that you own another home — surprises mid-process are how deals die. List your current home and begin your purchase search simultaneously rather than sequentially; the timelines overlap more naturally than most people expect.
Build flexibility into both contracts. On the sale side, negotiate a rent-back: after closing, you remain as a tenant paying the buyer’s carrying costs for up to 60 days, giving you a place to live while you close on the purchase. On the buy side, ask for a flexible closing date or a short post-occupancy by the seller. Align both closings within the same week if possible, and keep a cash buffer of at least three months of both housing payments — the National Association of Realtors’ transaction guidance stresses that simultaneous closings are common but rarely perfectly simultaneous, and the buffer is what keeps a one-week delay from becoming a crisis. Communicate relentlessly: your agent, your lender, both title companies, and both sides’ agents should all know the full picture.
What Can Go Wrong (and Your Backup Plans)
Plan for the failure modes. If your sale falls through, can you still close the purchase? Know your answer before you’re living it — whether that’s bridge financing, a 401(k) loan (risky, but sometimes the bridge you need), or a contract extension. If your purchase falls through after you’ve sold, where do you live? Line up the short-term rental option in advance, even if you never use it. If the appraisal on either property comes in low, have your response scripted: renegotiate, bring cash to cover the gap, or walk away per your contingency.
The meta-lesson: every simultaneous move needs slack in the system — slack in the budget, slack in the timeline, and slack in your expectations. The families who describe this process as “surprisingly smooth” aren’t luckier; they’re the ones who built buffers and backup plans before they needed them. Bankrate’s real estate calculators can help you model the double-payment scenarios so the worst case is a number on a spreadsheet, not a panic at midnight.
The Bottom Line
Selling while buying comes down to choosing your trade-off: sell first for safety (with temporary housing as the price), buy first for convenience (with double payments as the price), or thread the needle with a contingent offer (with market cooperation as the variable). Whichever you pick, get pre-approved with full disclosure, build rent-backs and flexible closings into your contracts, keep a three-month cash buffer, and over-communicate with everyone involved. It’s a high-wire act, but it’s one with a very good safety net — as long as you rig it before you climb.
Frequently Asked Questions
Can I use the equity from my current home for the new down payment?
Yes — through a home equity line of credit (HELOC), a bridge loan, or by timing the sale closing before the purchase closing. Each has costs and risks, so compare them against simply selling first.
What is a rent-back agreement?
An agreement where the seller stays in the home as a tenant for a set period (usually up to 60 days) after closing, paying the buyer’s carrying costs. It’s the most popular tool for bridging small timing gaps.
Will a home-sale contingency hurt my offer?
In competitive markets, yes — sellers prefer non-contingent offers. Strengthen yours by having your current home already listed or under contract, and consider a kick-out clause compromise.
How much extra cash should I have for a simultaneous move?
Aim for at least three months of both housing payments plus moving and storage costs. The buffer covers appraisal gaps, closing delays, and the overlap period without forcing panicked decisions.