House Hacking for Beginners: Live Cheap, Build Wealth
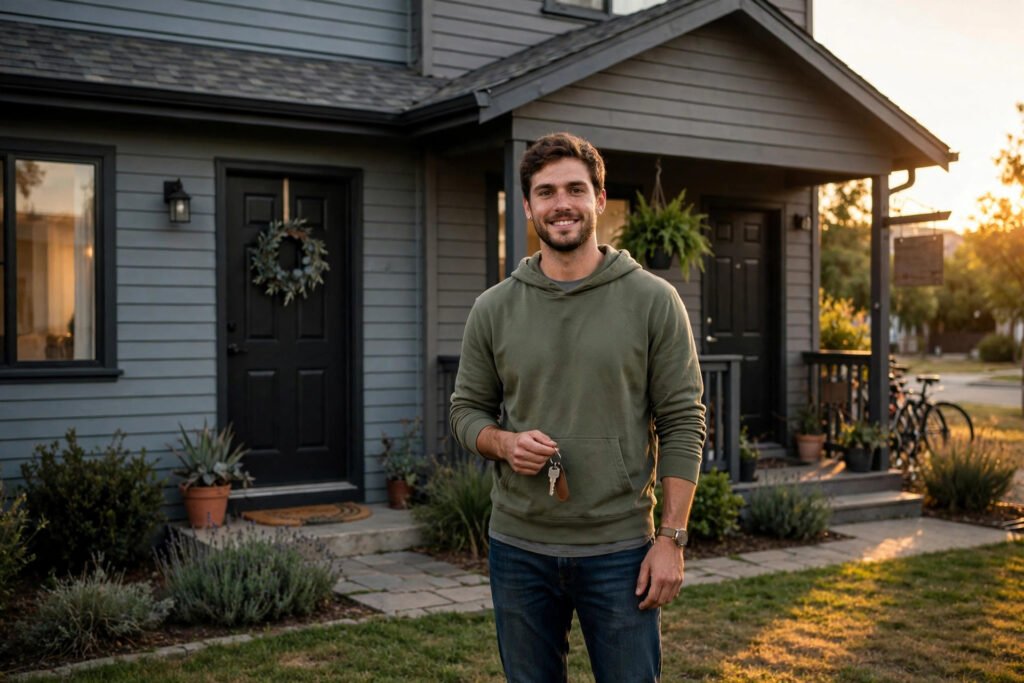
What if your housing payment — the biggest bill in most American budgets — shrank to zero? That’s the promise of house hacking: buying a property, living in part of it, and renting out the rest so tenants cover most or all of your mortgage. It’s not a get-rich-quick scheme; it’s the oldest wealth-building strategy in real estate, repackaged for the Instagram era. Teachers, nurses, and warehouse workers use it to live for free while their tenants build their equity. Here’s what house hacking actually is, the models that work for beginners in America, the real numbers, and the pitfalls that sink first-timers.
What House Hacking Actually Means
Strip away the buzzword and house hacking is simple: you buy a small multi-unit property (or a single-family home with rentable space), live in one unit, and rent the others. The rental income offsets your mortgage, taxes, insurance, and maintenance — ideally covering all of it, so you live for free while building equity and capturing appreciation. The classic version is the duplex, triplex, or fourplex bought with an FHA loan at 3.5% down: you must live in one unit for at least a year (that’s the owner-occupant requirement), and the other units’ rent pays the mortgage.
But the concept stretches wider than multifamily buildings. Renting out a basement apartment or ADU (accessory dwelling unit), leasing spare bedrooms to roommates, buying a single-family home and renting rooms — all count. Even short-term rentals qualify: some house hackers live in the primary bedroom and Airbnb the rest of the house on weekends. The unifying principle is that your residence becomes a partially income-producing asset instead of a pure expense. In high-cost cities where a starter home’s mortgage can devour 40–50% of a young worker’s income, that shift is life-changing: the difference between treading water and actually saving money each month.
The Beginner Models, Ranked by Difficulty
Start with the easiest on-ramp: the spare-bedroom rental. Buy (or keep) a home with an extra bedroom and rent it to a vetted roommate. Minimal extra cost, no zoning issues, no construction — just a lease, a background check, and house rules. The income is modest (a few hundred dollars monthly in most markets) but so is the complexity, making it the perfect first step to test whether you can tolerate the landlord life.
Level two is the ADU or basement conversion: adding a legal rentable unit to a single-family property. This requires real money ($30,000–$100,000+ depending on scope and market) and navigating local zoning and permits — but it creates a genuine second unit that appraisers value and lenders recognize. Level three, the true classic, is the 2–4 unit multifamily purchased with low-down-payment owner-occupant financing. FHA loans allow 3.5% down on up to four units; conventional options exist too. The rental income from the other units can even help you qualify for the mortgage, since lenders typically credit 75% of projected market rents. Each level up multiplies both the income and the responsibility — be honest about which landlord intensity matches your life. And from day one, treat the rental income like business revenue: our guide to handling taxes as a self-employed person covers the record-keeping discipline that rental income demands, since the IRS taxes it whether or not you think of yourself as a business.
Running the Numbers Before You Buy
House hacking lives or dies on math, so run it coldly. The beginner rule is the 1% test’s gentler cousin: total monthly rent from all units should comfortably exceed your PITI (principal, interest, taxes, insurance) plus a maintenance reserve. Let’s sketch a realistic example: a $350,000 duplex bought with 5% down at current rates might carry a PITI payment around $2,600. If each unit rents for $1,500, your tenant’s $1,500 covers more than half — you live for roughly $1,100 plus maintenance, versus $1,500+ renting a comparable apartment. In stronger rental markets, the tenant’s rent covers the entire payment and you live free while the loan amortizes and the property appreciates.
But budget the unsexy parts: vacancies (assume 5–8% annually), maintenance (the 1% rule — 1% of property value per year), capital expenditures (roofs, HVAC, appliances — budget monthly toward their eventual replacement), property management if you won’t self-manage (8–12% of rents), and insurance that covers rental activity (landlord policies cost more than homeowner’s). The IRS offers meaningful tax benefits — depreciation, deductible mortgage interest, repairs — detailed in IRS guidance on rental real estate, but taxes are a bonus, not the business plan. If the deal only works assuming perfect occupancy, zero repairs, and favorable taxes, it’s not a deal. The investors’ community at BiggerPockets is full of free calculators and brutally honest deal analyses worth studying before you offer on anything.
The Pitfalls That Sink First-Timers
The number one killer of house hacks is buying the wrong property: too expensive relative to rents, in a declining area, or needing more rehab than budgeted. House hacking doesn’t repeal the fundamentals — you still need the property to cash-flow on realistic numbers. Get a thorough inspection, verify actual market rents (not the seller’s optimistic pro forma), and check local landlord-tenant law before you buy: some cities have rent control, strict eviction procedures, or short-term rental bans that can demolish your strategy.
The number two killer is underestimating the human side. You are your tenants’ neighbor and their landlord — when the heat dies at midnight, you’re the one getting the call, and you’re getting it from ten feet away. Screen tenants rigorously (credit, income verification at 3x rent, landlord references, background check), use a real written lease, and enforce it consistently from day one; the “nice landlord” who lets late rent slide once creates a permanent expectation. Keep six months of total property expenses in reserve — vacancies and emergency repairs arrive together, as if coordinated. And maintain the boundary: friendly, professional, but not friends. The moment the relationship gets personal, the business decisions get impossible. Good personal finance management habits — separate accounts for the property, tracked expenses, emergency reserves — are what separate successful house hackers from cautionary tales.
Your First 90 Days: A Starter Checklist
Month one is education: read two books on rental property basics, run the numbers on 50 properties online (yes, 50 — it calibrates your instincts), get pre-approved with a lender experienced in 2–4 unit owner-occupant loans, and verify house hacking is legal for your target properties under local zoning. Month two is search: tour multifamily properties and ADU-suitable houses, verify rents with a property manager (most will give free rental analyses hoping for your business), and make offers based on your numbers, not your emotions. Month three is acquisition and setup: close, establish your reserve fund, set up separate banking, draft your lease (have a local attorney review it once), and list the unit.
Then live the strategy: bank the savings your reduced housing cost creates — that’s the actual wealth engine, whether it goes to the next property’s down payment, retirement accounts, or debt payoff. After the one-year owner-occupancy requirement, you can repeat: move into the next house hack and keep the first as a full rental. That’s how portfolios are built — not with genius, but with repetition of a sound, boring strategy.
The Bottom Line
House hacking works because it attacks the biggest line item in the American budget with the oldest tool in real estate: other people’s rent paying your mortgage. Start small (a rented bedroom), scale deliberately (ADU, then small multifamily), run honest numbers with real reserves, screen tenants like your finances depend on it (they do), and treat it as a business from day one. It’s not passive, it’s not instant, and it’s not for everyone — but for beginners willing to trade some convenience for financial velocity, few strategies in America build wealth faster.
Frequently Asked Questions
How much money do I need to start house hacking?
Less than most people think: FHA loans allow 3.5% down on 2–4 unit properties you live in — roughly $12,000–$15,000 down on a $350,000 duplex, plus closing costs and reserves. A spare-bedroom hack in a home you already own can cost nearly nothing to start.
Can I house hack with a single-family home?
Yes — by renting spare bedrooms, adding an ADU where zoning allows, or finishing a basement apartment. You won’t get multifamily-scale income, but you’ll meaningfully cut your housing costs with far less complexity.
Do I have to live in the property?
For low-down-payment owner-occupant loans (FHA, and most conventional primary-residence loans), yes — typically at least one year. After that you can move out and keep it as a full rental, or repeat the strategy on a new property.
Is being a landlord worth the hassle?
It depends on your temperament and systems. Rigorous screening, solid leases, and cash reserves eliminate most landlord horror stories. Many house hackers find 2–5 hours a month of management a fair trade for living nearly free.