
How to Get Business Funding Without a Credit Check (Legit Options)
Bad credit or no credit history doesn’t have to end your business plans — but it does change the playbook. If you’re wondering how to get business funding without a credit check, there are legitimate paths. There are also predators who specifically target desperate borrowers, so knowing the difference matters as much as knowing the options.
Here’s what’s real, what it costs, and the red flags that scream ‘scam.’
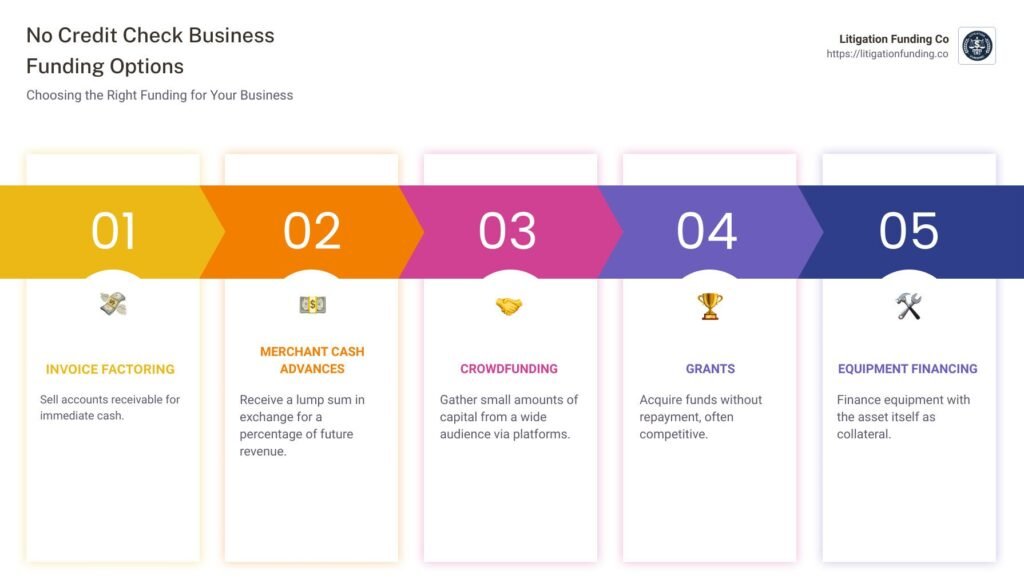
The short answer: legit no-credit-check options include revenue-based financing (Fundbox, OnDeck), microloans (Kiva 0% interest, SBA microloans), business grants, invoice factoring, equipment financing (the equipment is collateral), and crowdfunding. Avoid anyone guaranteeing approval or demanding upfront fees — those are scams.
Legitimate No-Credit-Check Funding Options
Revenue-based financing: companies like Fundbox and OnDeck advance cash against your business’s revenue and take a percentage of daily sales until repaid. They check your business bank statements, not your credit score. It’s fast (funding in 24–48 hours) but expensive — factor rates translate to 30–80% APR equivalents. Use it for short-term gaps, not long-term capital.
Microloans: Kiva offers 0% interest loans up to $15,000 with no credit check — you crowdfund from individual lenders, and repayment builds your credit. SBA microloans (up to $50,000 through nonprofit lenders) are more lenient than bank loans and come with mentoring. Accion Opportunity Fund serves borrowers traditional banks reject. These are slower but far cheaper than revenue-based options.
- Kiva: 0% interest, up to $15,000, no credit check
- SBA microloans: up to $50,000 via nonprofit lenders
- Revenue-based financing: fast but expensive (Fundbox, OnDeck)
- Invoice factoring: sell unpaid invoices for immediate cash
- Equipment financing: the equipment itself is the collateral
- Grants: free money, but competitive and slow (see below)
Grants: Free Money That Takes Work
Business grants don’t require repayment or credit checks — they require effort. Good sources: Grants.gov (federal), your state’s small business development center, Amber Grant for women-owned businesses ($10,000 monthly), NASE grants, and local economic development programs. Corporate grants (FedEx, Visa, Comcast RISE) run annual competitions.
Be realistic: grants are competitive, applications take hours, and disbursement takes months. Treat grant applications as a background process while you fund the business another way — not as the plan. And never pay anyone who ‘guarantees’ grant money; that’s always a scam.
Funding That Doesn’t Look Like Funding
Sometimes the best no-credit-check funding isn’t a loan at all. Customer pre-sales: sell the product or service before it exists (deposits, Kickstarter, presold packages) — this is how many businesses should start anyway, because it validates demand. Supplier terms: negotiate net-30 or net-60 payment with suppliers, effectively borrowing interest-free. Business credit cards with 0% intro APR: some don’t require great credit, and they build your history if paid off.
And the unglamorous champion: revenue. Starting lean and funding growth from profit is slower but leaves you owning 100% with zero debt. Many of the most durable small businesses never took outside funding at all — which is exactly why starting a home business with no money is a viable strategy, not just a fallback.
Scams Targeting Bad-Credit Borrowers
Predators know you’re stressed, so learn their playbook. Red flags: guaranteed approval regardless of anything, upfront fees before disbursement (‘processing fee,’ ‘insurance’), pressure to decide immediately, no physical address or verifiable business history, and offers arriving via unsolicited text or social media DM. Legitimate lenders never ask for gift cards, wire transfers, or cryptocurrency as fees.
Merchant cash advances deserve special caution: they’re legal, but the effective APRs (often 100%+) and daily automatic withdrawals have killed countless small businesses. If someone offers you fast cash against future sales, read every word, calculate the true cost, and consider whether you’d be better off improving your credit score to qualify for a proper business loan instead — sometimes the best funding strategy is a six-month credit repair sprint.
How Can I Get Business Funding Without a Credit Check for a Startup With No Revenue?
No credit and no revenue is the hardest combination — most no-credit-check options in the main guide assume at least some cash flow. What’s left: Kiva (0% loans up to $15,000, judges your story and network, not your finances), grants (slow but real — start applications now as a background process), and pre-sales (sell before you build; the purest validation and the cheapest capital).
Beyond that, get creative about what ‘funding’ means. Equipment financing works with no revenue because the equipment is the collateral — a $5,000 commercial mower financed this way starts a landscaping business with no credit check and no revenue history. Supplier terms (net-30) fund inventory interest-free. And business credit cards with 0% intro APRs sometimes approve thin files — but only if you’re certain revenue arrives before the promo expires, or the 25%+ APR will eat you alive.
The honest strategic question: should you borrow at all right now? Pre-revenue borrowing at high cost is how businesses die young. The safer sequence is often: start the leanest version with no money, generate the first $1,000–$5,000 in revenue, then borrow against that traction at better terms. Revenue is the cheapest credential in lending — even a little of it transforms your options. Six months of scrappy operation beats six months of debt nearly every time.
One more path for pre-revenue founders: pitch competitions and incubators. Local Small Business Development Centers, SCORE chapters, and economic development agencies run competitions with $5,000–$$50,000 prizes — no credit check, no repayment, just a good pitch and a viable plan. The application process itself sharpens your business thinking, and even losing finalists often get mentoring and connections worth more than the prize. It’s free money for the effort of applying well.
Related reading: how to improve your credit score to qualify for a business loan · how to start a small business from home with no money
The Bottom Line
Real no-credit-check options: Kiva (0%), SBA microloans, revenue-based financing (fast but pricey), invoice factoring, equipment financing, grants, and customer pre-sales. Never pay upfront fees or trust ‘guaranteed approval.’ And consider whether six months of credit repair might open cheaper doors than any no-check option.
Sources: SBA: microloan program · Kiva: 0% small business loans
1 thought on “How to Get Business Funding Without a Credit Check (Legit Options)”